growth in lithium-ion battery deployment between 2020 and 2025
MNS GRAPHITE S.A. · ITABELA PROJECT
Flake graphite in the Bahia - Minas Graphite Province
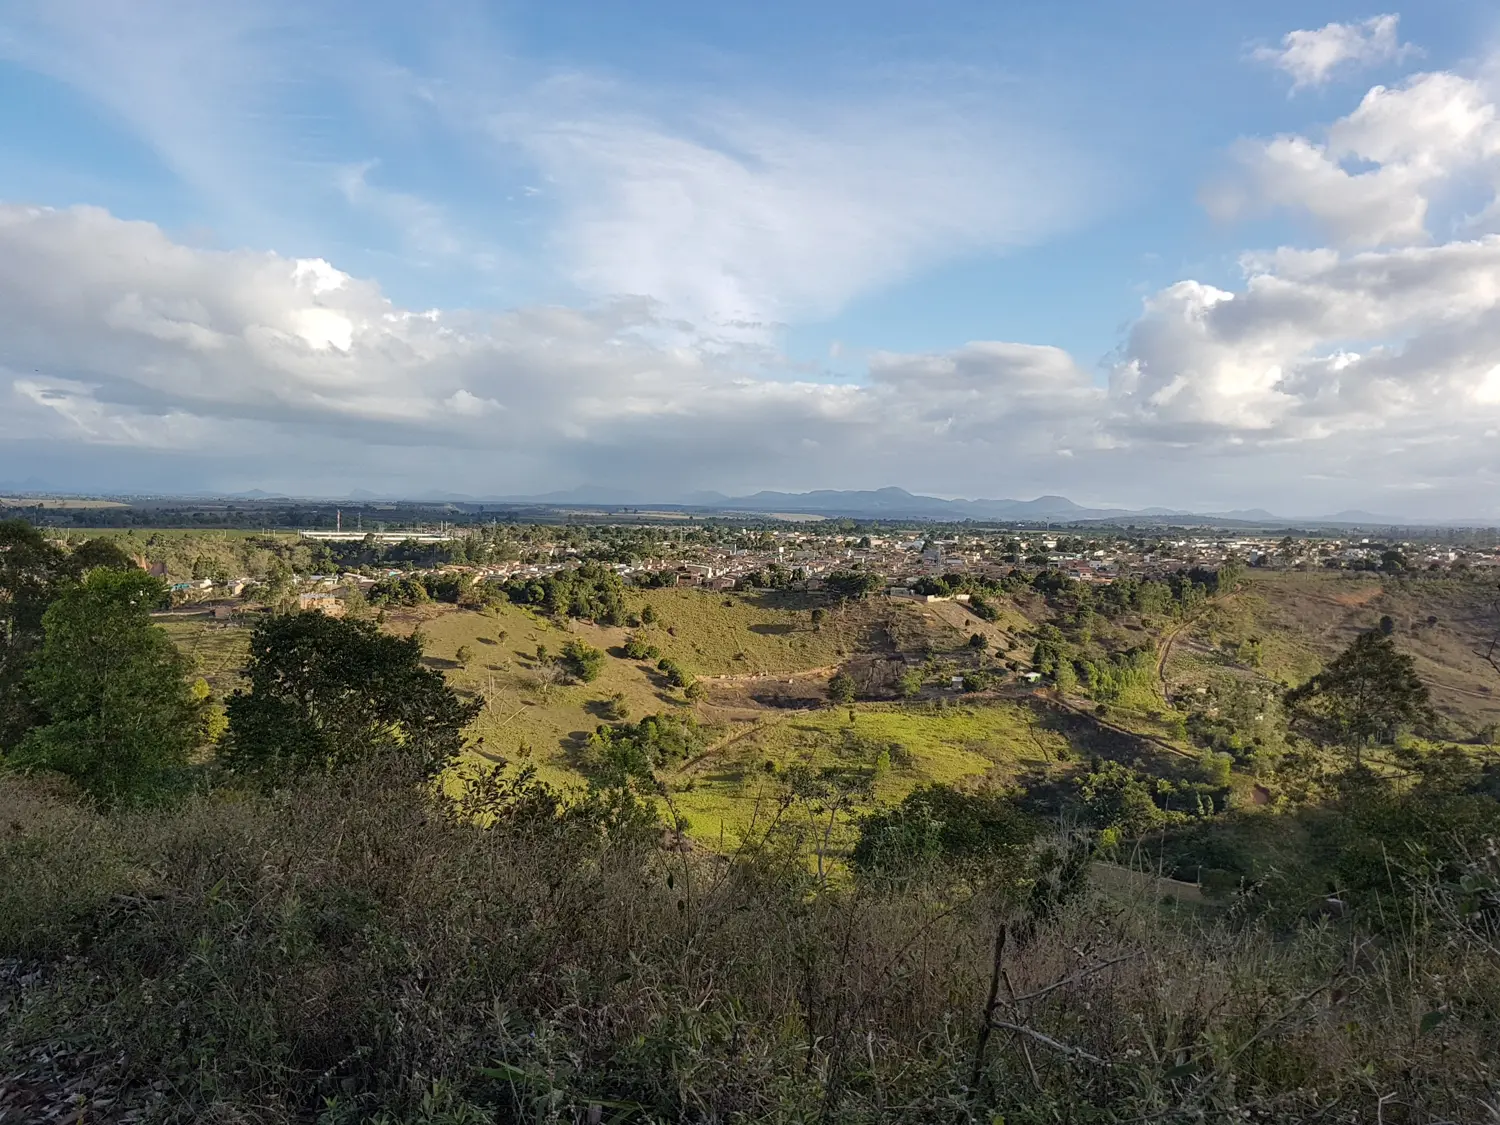
An exploration project next to a producing mine — Itabela, southern Bahia, Brazil.
FROM WRITING TO ELECTRIFICATION
An ancient mineral at the centre of the new electric economy
Graphite is a naturally occurring crystalline form of carbon. Its layered structure combines electrical and thermal conductivity, high-temperature resistance, lubricity and processability — properties that explain a centuries-long journey from early writing tools to the batteries powering electric vehicles.
ConductiveRefractoryLubricatingVersatile
A HISTORY OF ADAPTATION
The same structure, increasingly strategic applications
- 0116th century
From marking to casting
High-purity graphite from Borrowdale, England, began to be exploited for writing and drawing, casting moulds and lubrication.
- 021789
A mineral gains its name
Abraham Gottlob Werner adopted the name graphite, derived from the Greek graphein — to write — distinguishing the mineral from lead.
- 03Industrial era
Heat, friction and electricity
Refractories, steelmaking, crucibles, electrodes, motor brushes, friction materials and lubricants expanded its industrial role.
- 041990s
The lithium-ion era
The commercialisation of lithium-ion batteries opened the application that now positions graphite as a strategic anode material.
- 052020–2025
Rapid scale-up
Global lithium-ion battery deployment increased more than sixfold, driven by electric vehicles and energy storage.
- 06Towards 2040
Demand and supply security
Electrification supports a strong growth outlook while governments and manufacturers seek more diversified supply chains.
WHY GRAPHITE MATTERS NOW
The anode has transformed an industrial mineral into a strategic asset
Graphite is the principal active anode material in most commercial lithium-ion batteries. These batteries use more graphite by mass than any other battery material — including lithium. At the same time, mining, purification and anode-material manufacturing remain highly concentrated, increasing the strategic value of technically qualified new supply chains.
of today’s lithium-ion battery market is in electric vehicles and energy storage
of global refined supply is controlled by graphite’s leading supplier: China
THE INVESTOR LENS
Finding graphite is the beginning. Delivering a qualified product is the objective.
The value of a deposit depends on more than carbon content. Flake size and distribution, mineralogy, metallurgical recovery, purity, impurities, processing costs, infrastructure and product consistency determine which markets can be served and at what margin.
- 01Ore
Cg grade, mineralogy and flake-size distribution.
- 02Concentrate
Metallurgical recovery, purity and flake preservation.
- 03Anode material
Spheronisation, purification, coating and impurity control.
- 04Qualification
Performance testing, consistency and customer approval.
FROM THESIS TO PROJECT
This is the context in which the Itabela opportunity begins
The Itabela Project seeks to determine whether flake graphite occurrences, geophysical targets and its location in the Bahia–Minas Graphite Province can support a technically competitive project. Grades, continuity, resources and metallurgical performance still depend on assays, drilling and testing — precisely the next de-risking milestones.
Reference sources: IEA · Global Critical Minerals Outlook 2026; IEA · Global EV Outlook 2026; USGS · Mineral Commodity Summaries 2026; U.S. Department of Energy.
THE OPPORTUNITY
2,589.63 haMineral rights
3Contiguous permits
138Mapped outcrops
10Geophysical lines
A new project in a proven district
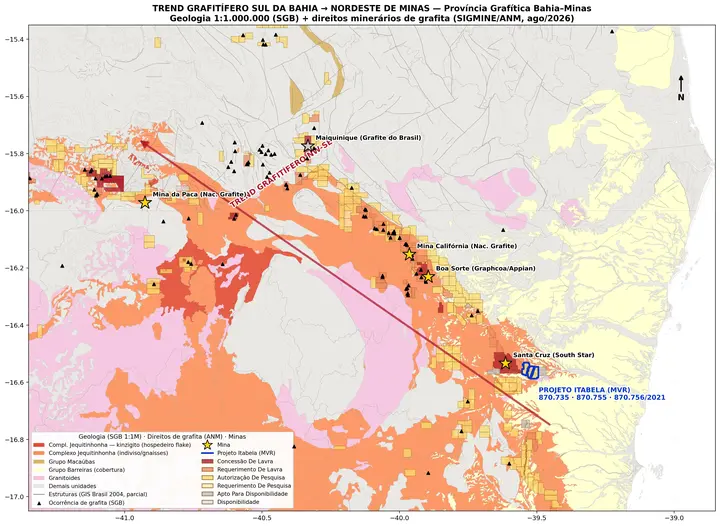
Three contiguous flake graphite permits on the main trend of the Bahia–Minas Graphite Province — the geology that supports almost all of Brazil's graphite production.
World-class district
The Bahia–Minas Graphite Province has the ideal metamorphic grade for medium to coarse flake — the highest-value market fraction.
Producing mine nearby
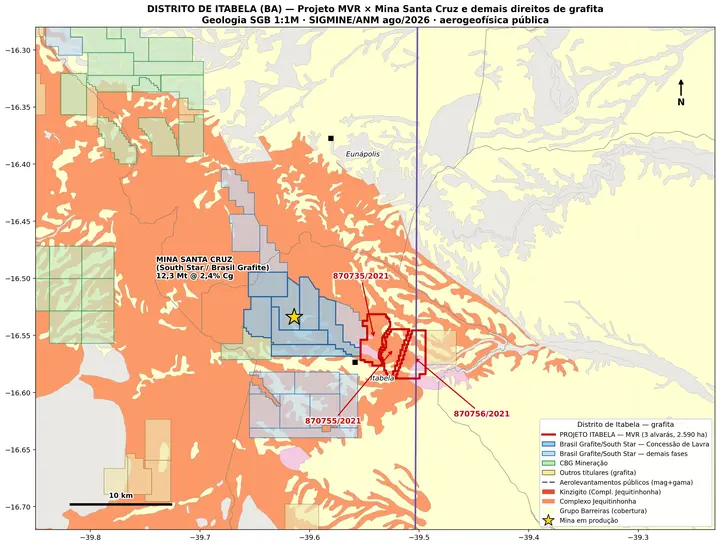
South Star's Santa Cruz Mine is close to the project: 12.3 Mt at 2.40% Cg, an open-pit saprolite operation now in production.
Secure mineral tenure
2,589.63 hectares covered by three contiguous ANM exploration permits next to the BR-101 highway, with no pending applications.
Targeted exploration
1:10,000 mapping across 138 outcrops and ten geophysical lines have produced ranked exploration targets.
Focused due diligence
Four months to confirm the anomalies and obtain the project's first grades through GIS integration, IP, shallow drilling and Cg assays.
Investment-ready vehicle
MNS Graphite S.A., with corporate governance, equity-based investment and a shareholders' agreement.
STRATEGIC LOCATION
At the heart of the province's Bahia segment
The Itabela Project lies next to the BR-101 highway in the Porto Seguro–Eunápolis region, approximately 8 km from the Santa Cruz Mine.
MARKET
The battery anode is graphite — and supply is dominated by China
Projected growth in natural graphite demand by 2036.
Of global spherical graphite is controlled by China — along with more than 95% of synthetic anode material.
Large-flake price range in 2025, with a 40–80% premium over fine flake.
Battery anodes' share of natural graphite consumption
In the short term, conventional flake remains weak amid Chinese oversupply and softer steel demand. The thesis is structural and long-term, anchored in anode growth and the potential premium for non-Chinese supply.
BAHIA–MINAS GRAPHITE PROVINCE
Brazil's graphite industry is here
The Bahia–Minas Graphite Province has concentrated Brazil's flake graphite production for decades — and investment capital is flowing back into the region.
Nacional de Grafite
Minas GeraisDecades of continuous production. It operates the Fazenda Califórnia Mine in Salto da Divisa at approximately 70,000 tpa — a global benchmark for flake graphite outside China.
Santa Cruz · South Star
Bahia — in productionThe first commercial-scale mine on the Bahia side of the province: shallow saprolite, open-pit mining and free-dig material. It lies in the same district as MNS and is the direct analogue for the Itabela Project.
Boa Sorte · Graphcoa (Appian)
Bahia — under developmentOperating since December 2024 with initial capacity of 5,500 tpa and a proposed expansion to 25,500 tpa under study. Appian has announced more than BRL 2 billion of investment in the district through 2029.
Why this matters: the Itabela Project sits at the heart of the province's Bahia segment — with proven geology, established infrastructure and neighbouring operations that validate the business model.
THE GRAPHITE
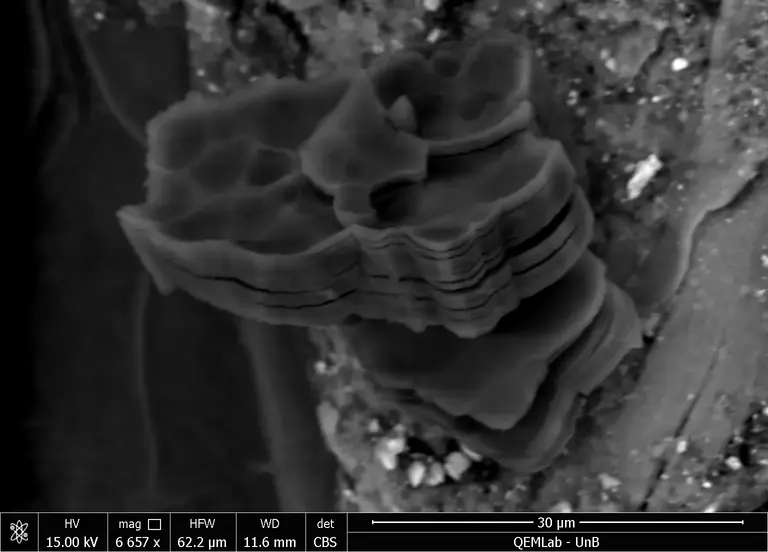
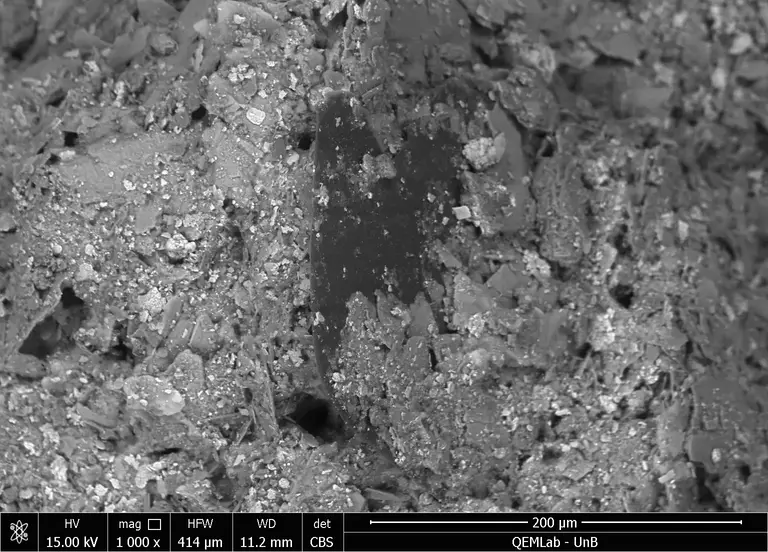
Outcrop samples show the presence of jumbo flakes
THE ORE
Value lies in flake size
Flake graphite is the feedstock for spherical graphite and premium applications. At Itabela, medium to coarse flake is visible in more than 50 outcrops; grade and particle-size distribution still require laboratory confirmation.
| Category | Mesh | Opening | Value position |
|---|---|---|---|
| Jumbo | +50# | > 300 µm | Highest premium |
| Large | +80# | 180–300 µm | High premium |
| Medium | +100# | 150–180 µm | Mid-range |
| Fine | −100# | < 150 µm | Market baseline |
WORK COMPLETED
Two surveys, one focused system
Geological mapping
- 138 outcrops; 91 described and 58 sampled.
- More than 50 with visible medium to coarse flake graphite.
- NW–SE structural control, including fold hinges and a shear zone.
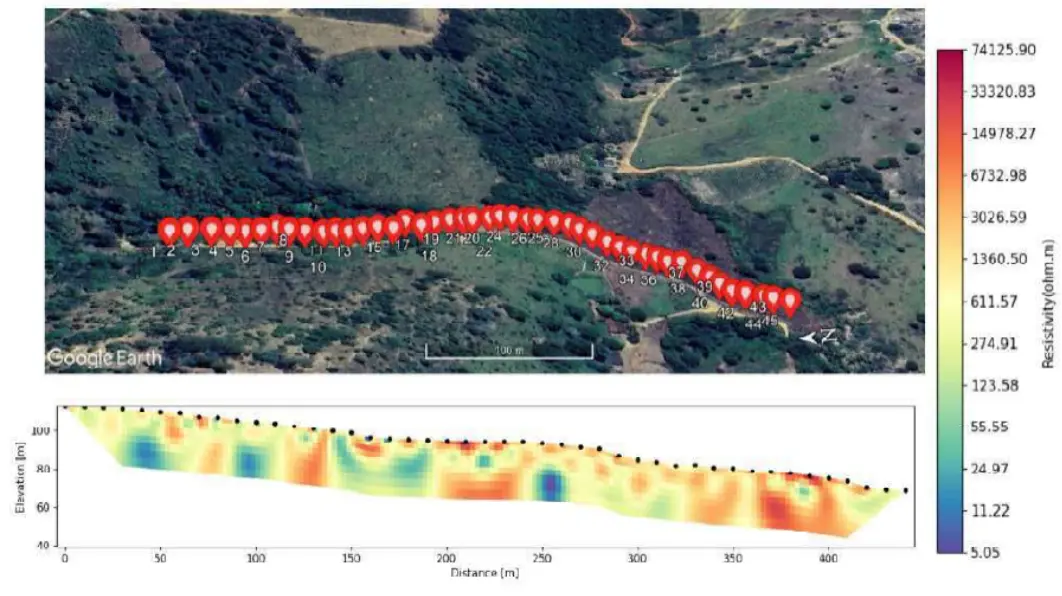
Electrical resistivity
- Ten dipole-dipole lines completed in January 2026.
- Strong, discrete and coherent conductive anomalies.
- L8 and L9 display the priority signatures for drilling.
GEOLOGY
How an Araçuaí flake deposit forms
- 1
Source
Organic-rich sediments deposited in Neoproterozoic basins.
- 2
Metamorphism
High-grade metamorphism in the Araçuaí Orogen recrystallises carbon into flake: the higher the temperature, the larger the flake.
- 3
Structure
NW–SE folding and shearing thicken and concentrate graphitic horizons.
- 4
Weathering
Tropical saprolitic weathering softens the rock, liberates the flake and enables free-dig mining.
THE ROCK
It is saprolite.
That changes the economics.
The mapped mineralisation is most commonly hosted in friable saprolite — the same profile that supports the neighbouring mine.
- Surface mineralisation in friable material.
- Shallow pit and an expected low strip ratio.
- Validation by auger and air-core drilling; deep drilling only after the go decision.
- Flake liberated in a soft matrix, with potentially lower comminution energy subject to confirmation.
TARGET SELECTION
Where to investigate first — and why
| Line | ERT signature | Interpretation | Priority |
|---|---|---|---|
| L8 | Min. ~5 Ω·m; contrast >1,000× | Subvertical, near-surface conductor extending to ~26 m. | P1 |
| L9 | Min. ~27 Ω·m; discrete conductors | Cluster of focused conductors with cores at 12–18 m. | P1 |
| L5 | Min. ~57 Ω·m | Focused conductor on the valley floor, with its base at ~12 m. | P2 |
| L4 | Min. ~76 Ω·m | Conductive zones at depth, with a core at ~12 m. | P2 |
Conceptual exploration target — not a mineral resource. Combining the anomaly geometry with the assumed grade of the analogue produces a base case of approximately 12.4 Mt and 300 kt of contained graphite. No drilling or grade assays have been completed on the project; this estimate does not constitute a mineral resource or reserve.
MINERAL RIGHTS
2,589.63 hectares, secured
Three contiguous permits
ANM proceedings 870.735/2021, 870.755/2021 and 870.756/2021. Exploration permits granted and ownership consolidated.
Holder: MNS Graphite S.A.
Successor through the transformation of MVR Grafite Mineral Ltda., retaining the same corporate registration and legal relationships.
Established logistics
Next to the BR-101 highway in the Porto Seguro–Eunápolis region, with power and paved access already proven by the neighbouring mine.
Clear regulatory pathway
Exploration under way, ANM Final Exploration Report due in April 2028, followed by a mining concession application.
WORK PROGRAMME AND INVESTMENT
Four stages, defined by their milestones
Each stage is designed to deliver a verifiable milestone — and achievement of that milestone authorises the next stage.
014 months
Due diligence
GIS integration; Cg assays on 58 samples; IP over priority lines; shallow air-core or auger drilling.
MILESTONEConfirmation of the anomalies, graphite quality and Cg grades, followed by a go/no-go decision.
02January 2028
Systematic exploration
ERT and IP across the three permits; grid drilling; approximately 2,000 chemical assays; mineralogical characterisation and metallurgical studies.
MILESTONEMineral resources and ANM Final Exploration Report.
03December 2028
PAE / PFS
Infill drilling, bench-scale flotation tests and technical-economic studies.
MILESTONENI 43-101 resource, PFS, PAE and mining concession application.
04December 2029
Feasibility
Pilot plant, engineering, market studies and mine design.
MILESTONEFeasibility study and mine development decision.
Investment through a primary share issue or share acquisition, in milestone-linked tranches with an investor go/no-go decision at each gate. Amounts and terms are under discussion and subject to NDA.
PROCESSING
Value is determined in flotation — and it starts early
In graphite, quality and grade define the premium; metallurgy determines whether that premium can be achieved. Recovery, size distribution and purity determine the basket price.
Established flowsheet
Saprolite avoids heavy crushing: scrubbing, staged grinding and flotation.
District precedent
Santa Cruz produces 95–99% Cg concentrate with approximately 65% large flake.
What will be measured
Particle-size distribution, recovery and purity — from bench testing to the pilot plant.
Downstream upside
Spherical graphite and anode material provide strategic optionality and are not included in the base case.
THE COMPANY
MNS Graphite S.A. — investment-ready, with aligned capital
AM
Alexandre Mendonça
Management and business development
Business Administrator with a master's degree in Business Development Management. More than 20 years of experience in management, entrepreneurship and business development, including direct experience in the operational, commercial and financial management of mining activities.
AN
Augusto Nobre Gonçalves
Mineralogy, materials and mineral processing
Geologist from USP; MSc and PhD in Materials Engineering and Nanotechnology; postdoctoral research in Mineralogy. Professor at the University of Brasília Institute of Geosciences and consultant in mining and mineral processing.
ES
Elmer Prata Salomão
Strategy, technical origination and capital markets
Geologist from the Ouro Preto School of Mines and founder of GEOS. Former Director-General of DNPM, former CPRM board member, and involved in the formation and fundraising of Verena Minerals and Cerrado Gold.
DUE DILIGENCE
Simple, low-cost and capable of unlocking the project
The objective is to confirm the first Cg grades from a system that has already been mapped and ranked — the lowest-cost test of a model that has already become a mine nearby.
Contact usImportant notice
No mineral resource or reserve is declared. The results are exploration results: surface geological mapping and ground geophysics. No drilling or graphitic carbon grade assays had been completed on the project as of the presentation date, and nothing has been used to estimate a mineral resource under CBRR/CRIRSCO, NI 43-101 or JORC.
An anomaly is not a deposit. Similar conductive signals may result from clay, moisture or sulphides. Comparisons with Santa Cruz and other projects are analogies, not claims of equivalence in grade, scale or quality.
Plans, schedules, budgets and prices are subject to exploration, technical, regulatory, market and financing risks. This website does not constitute an offer of securities or investment advice.
Technical basis presented in the investor deck: MVR Grafite Mineral (Feb 2025), Phygeo (Jan 2026), ANM and independent technical due diligence (Jun 2026). Technical review: Elmer Prata Salomão, geologist.
GRAPHITE INSIGHTS